
Conventional Mortgage
Traditional home financing with competitive rates, for buying your first home or your next one. Decisions made locally by people who know this market.
Rates change. See Current Rates for today’s figures.
What a Conventional Mortgage Is
A conventional mortgage is not insured or guaranteed by a government program. That usually means fewer program restrictions on the property and the borrower, and it means the rate and terms rest on your credit, your down payment, and the property itself. It is the most common way people finance a home.
First Mortgages
As low as
6.599%APR²
APR = Annual Percentage Rate. Rates effective October 5, 2026 and subject to change without notice. Monthly principal and interest is based on a $320,000 mortgage and excludes taxes and insurance, so the actual obligation is higher. Minimum loan $100,000, maximum $832,750, 720 minimum credit score, up to 80% loan to value, owner occupied single-family or conforming condo in CT or RI, first lien only. All loans subject to credit approval.
Apply for a MortgageView all first mortgage rates and payment examples
| Product | Term | Rate | APR | Monthly P&I |
|---|---|---|---|---|
| 30 Year Fixed Conventional | 30 Year | 7.25% | 7.313% | $2,182.96 |
| 20 Year Fixed Conventional | 20 Year | 7.00% | 7.081% | $2,480.96 |
| 15 Year Fixed Conventional | 15 Year | 6.50% | 6.599% | $2,787.54 |
What You Should Know
Fixed or Adjustable
Choose a rate that stays the same, or one that can change over time.
Primary, Secondary, or Investment Property
Available for a main residence, and often for a second home or investment property.
Mortgage Insurance
Required on any conventional loan with a down payment under 20 percent, or a loan-to-value above 80 percent.
Local Lending. Personal Guidance
Talk with a local lender first, know your options, and keep your mortgage local with loans underwritten and serviced here.
Connect with Waypoint’s Mortgage Specialist
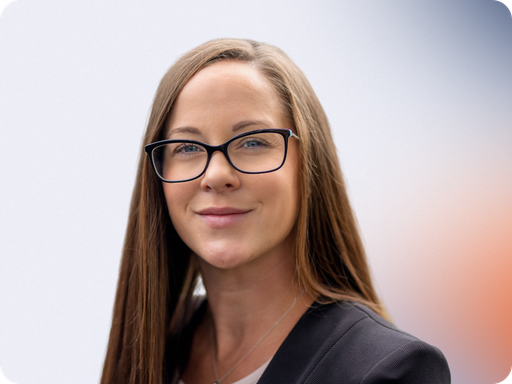
Buying a home is a big milestone, and Kimberly Tondreau is here to make the financing process easier. Whether you’re a first-time buyer, moving up, or investing, Kim will help you explore your mortgage options and find a solution that fits your goals and budget.
Kimberly Tondreau
AVP, Mortgage Specialist
Waypoint Credit Union
NMLS ID# 1739761
860-885-3637
Ready to Connect?

Call or Text Us
Call 860-885-3637, Monday to Thursday 9:00am to 4:30pm, Friday 9:00am to 5:00pm. Alternatively, text 860-917-3113.
Book an Appointment
Book an appointment with Kimberly at your local Waypoint branch.
What You Will Need
Every application is different, but a Waypoint lender will generally look at your income, your credit history, your existing debts, and how much you have for a down payment. Bring what you have and we will tell you where you stand.
- Proof of income and employment
- Recent bank and asset statements
- Your credit history
- There is no minimum credit score for a Conventional Mortgage.
Common Questions
As low as 3 percent down for standard conventional loans, including Fannie Mae and Freddie Mac options and special first-time buyer programs, for borrowers with good credit. A primary residence typically starts around 5 percent down. A second home or investment property generally requires 10 to 15 percent down. Putting 20 percent down eliminates private mortgage insurance and gives the lowest monthly payment.
That depends which option you choose. Fixed-rate loans keep the same rate for the life of the loan. Adjustable-rate loans start fixed and can change after that. A lender will walk you through both.
Conventional loans are available beyond designated rural or tribal areas, but loan amounts are subject to county-specific limits that are updated annually.
Talk it through with someone who lends here.
Local decisions. No obligation.
A short conversation before you apply tells you what you can realistically borrow and what it will cost. Book a time at any Waypoint branch, or start online and we will pick it up from there.
Important Disclosures
Equal Housing Lender. NMLS #404962.